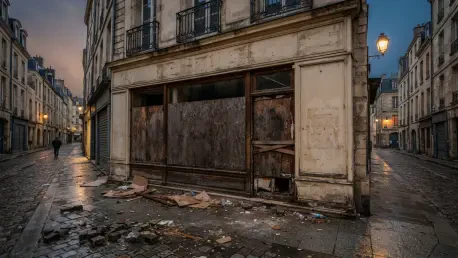
The charred remains of the Limoges town hall stand as a haunting monument to the volatile October 2024 protests that left the French insurance industry grappling with a staggering €1.2 billion bill. This eruption of civil unrest was not merely a brief moment of chaos; it represented a fundamental fracture in the relationship between the state, the private sector, and the safety nets designed to protect the national economy. As the smoke cleared from the streets of major urban centers, a chilling financial reality emerged, revealing that the cost of social instability has reached a scale that traditional insurance models were never built to withstand. For thousands of small business owners, the recovery has become a labyrinth of paperwork and technical exclusions that threaten to turn temporary closures into permanent failures.
While the nation’s largest insurance carriers have maintained their solvency, the sheer magnitude of the 2024 damage has exposed a critical vulnerability within the French economy. The demonstrations, which began as peaceful calls for economic reform, quickly spiraled into a nationwide wave of looting and arson that resulted in nearly 2,400 arrests. Beyond the immediate physical destruction, the event signaled a shift in the nature of domestic risk. This story matters because it marks the moment when civil commotion ceased to be an occasional property peril and officially became a systemic threat on par with natural disasters. Without a robust and timely intervention, the insurance gap currently facing French retailers could trigger a mass withdrawal of coverage from high-risk neighborhoods, leaving urban centers economically hollowed out.
A Billion-Euro Bill and the Smoldering Remains of Limoges
In the cooling embers of the October 2024 unrest, the financial tally began to climb with a speed that shocked even seasoned industry veterans. The violence was not localized to a single district but pulsed through the arteries of several major cities, with Limoges becoming a symbolic epicenter after its historic town hall was targeted. This surge in nationwide protests, initially centered on cost-of-living grievances, saw over 3,000 small and medium-sized enterprises fall victim to looting, vandalism, or fire. The resulting €1.2 billion estimate for insured losses has forced a massive reallocation of capital within the property and casualty sector, as firms scramble to address the immediate liquidity needs of policyholders.
The human element of this crisis is found in the hundreds of shopkeepers who arrived at their premises to find glass-strewn floors and empty shelves. For these individuals, the “billion-euro bill” is not an abstract macroeconomic figure but a direct threat to their livelihoods. While the government provided some relief through partial unemployment benefits for displaced staff, the core of the recovery depends on the speed of insurance payouts. However, the complexity of assessing thousands of simultaneous claims has slowed the process, creating a bottleneck that has left many storefronts boarded up months after the last sirens faded. The scale of the destruction suggests that the recovery will be measured in years, not weeks, as the retail sector tries to rebuild consumer confidence alongside physical infrastructure.
Why the 2024 Unrest Signals a Structural Crisis
The trajectory of civil commotion in France reveals a disturbing trend of escalating costs that the industry can no longer treat as a series of isolated incidents. To put the current €1.2 billion loss in perspective, one must look back at the suburban unrest of 2005, which cost insurers a relatively modest €200 million. By the time the nation faced the 2023 riots, that figure had quadrupled to €800 million. The jump to the present billion-euro threshold confirms that the severity of these events is outpacing inflation and typical risk modeling. This trend suggests a fundamental change in the tactics of civil disorder, where high-value commercial targets and public infrastructure are increasingly at risk.
This shift indicates that civil unrest has transitioned into a “systemic catastrophe,” mirroring the behavior of floods or earthquakes where damage is highly correlated across a wide area. In traditional insurance, risks are usually independent; a fire at one shop does not mean the shop next door is more likely to burn. Modern riots, however, operate on a contagion model, triggering thousands of claims at once and overwhelming local adjusters. This “market failure” is particularly acute in high-risk urban areas and overseas territories like New Caledonia, where insurers are beginning to view the risk as unpriceable. If coverage becomes too expensive or completely unavailable, these regions face a permanent economic disadvantage, further fueling the social tensions that led to the unrest in the first place.
The Financial Fallout and the Legislative Limbo
The current crisis is exacerbated by a significant “legislative gap” that has left the insurance market without its intended safety net. In early 2024, the government passed the 2026 Finance Law, which introduced Article 171—a provision specifically designed to create a state-backed riot insurance pool. This pool was intended to mutualize the risk of civil disorder, providing a government guarantee to help absorb losses that exceed a certain threshold. However, due to the lengthy process of obtaining European Commission approval for state-aid measures, this system is not scheduled to become fully operational until January 1, 2027. This means the €1.2 billion bill from the October riots must be absorbed entirely by the private market, without the cushion of the state-guaranteed fund.
This timing dilemma has left private insurers and international reinsurance panels to foot a bill that was legally recognized as a state responsibility just months prior. Beyond the timing of the legislation, a widening chasm exists between insured losses and the true economic toll on the French retail sector. Standard insurance policies often contain restrictive clauses that exclude or severely cap coverage for looting and the destruction of vehicles held under third-party contracts. The most damaging exclusion, however, is Business Interruption (BI). Many retailers who suffered no direct physical damage were nonetheless forced to close for weeks due to city-wide curfews or proximity to violence, leaving them with massive trade losses for which they will receive no compensation.
Legal Realities and the Struggle for Recovery
In the wake of the 2024 riots, the legal battleground has shifted toward Article L.211-10 of the Internal Security Code, which outlines the conditions under which the state can be held liable for damage caused by violent “gatherings.” This statute theoretically allows insurance companies to pursue subrogation rights, suing the government to recover the money paid out to policyholders. Yet, the path to recovery is obstructed by a complex judicial distinction between “spontaneous” and “organized” violence. If a court decides that the October events were the result of a pre-planned political movement rather than a spontaneous crowd, the state’s liability is significantly reduced, potentially leaving insurers with no way to recoup their losses.
Financial analysts from DBRS Morningstar have noted that while these losses will dent the annual earnings of major French carriers, they do not yet pose a threat to credit ratings. However, the long-term stability of the market hinges on the successful launch of the Caisse Centrale de Réassurance (CCR) pool. This upcoming framework will be funded by a mandatory 1.5% premium contribution from all property policyholders, creating a multibillion-euro reservoir to handle future unrest. Industry leaders have warned that without this state-backed mechanism, the private market might be forced to implement “mandatory writing” restrictions, where a central authority must intervene to force insurers to provide coverage to businesses in high-risk zones that have been blacklisted by traditional underwriters.
Strategies for Navigating the Evolving Risk Landscape
For businesses operating in an increasingly volatile world, the lessons of the 2024 crisis have necessitated a total rethink of risk management strategies. The most successful firms have realized that standard multi-risk policies are no longer a sufficient shield against modern civil commotion. To bridge the insurance gap, companies are now looking toward standalone “Strikes, Riots, and Civil Commotion” (SRCC) policies. These specialized products offer broader protections that specifically include looting and vandalism without the restrictive caps found in general property wordings. Furthermore, the adoption of Non-Damage Business Interruption (NDBI) coverage has become a priority, as it allows businesses to claim for lost revenue even when their storefront remains physically intact but inaccessible.
The French approach to riot insurance is also serving as a critical case study for global markets, including the United Kingdom. By moving toward a model of “mandatory writing” and state-backed reinsurance, France has attempted to maintain urban economic stability through proactive regulation. Global firms have responded by treating civil unrest as a core pillar of their disaster recovery planning, ensuring they maintain financial liquidity through diverse insurance placements in specialized markets like Lloyd’s of London. These strategies ensured that when the next wave of instability arrived, businesses were not caught in the same legislative or financial limbo that characterized the aftermath of the October events.
The 2024 unrest ultimately demonstrated that the traditional boundaries of property insurance were insufficient for the challenges of modern social volatility. Policymakers and industry leaders recognized that a purely private response to systemic civil commotion was no longer sustainable in a high-risk environment. Stakeholders prioritized the accelerated development of the CCR pool, acknowledging that state-backed reinsurance was the only viable path to protect the retail sector from total market withdrawal. Companies that proactively adopted standalone SRCC and NDBI policies successfully navigated the recovery process with greater financial resilience than those who relied on standard contracts. The transition toward a mutualized risk model proved essential for maintaining the economic health of French cities, as the nation prepared for a more secure and better-insured future. This shift in perspective transformed how political violence was priced and managed, ensuring that the hard-won lessons of the recent crisis were translated into lasting structural reforms.