Under current North Carolina law, if a covered peril contributes to a loss in any capacity, the insurer remains liable regardless of other contributing factors. This legal reality has significantly reshaped the landscape for business owners and property managers across the state, ensuring that the protections they pay for are not easily dismantled by technicalities. The recent decision by the United States Court of Appeals for the Fourth Circuit in the case of Wake Chapel Church, Inc. v. Church Mutual Insurance Company highlights this shift, affirming a million-dollar jury verdict that favors the policyholder. As 2026 progresses, the legal community is witnessing a stabilization of insurance standards that prioritize the reasonable expectations of the insured over the narrow interpretations often favored by massive insurance carriers. This judicial momentum serves as a critical shield for local organizations, reinforcing the concept that all-risk policies are designed to provide comprehensive security against fortuitous events, even when complex variables are at play during a loss event.
Understanding the Wake Chapel Church Precedent
Analyzing the Case Background
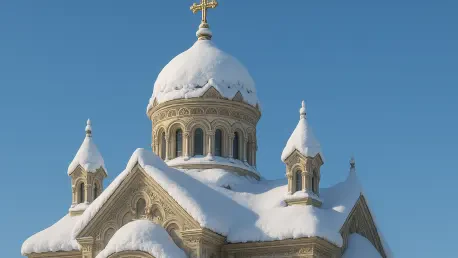
The dispute at the heart of this transformation began following a significant snowstorm in late 2018, which led to the structural failure of a sanctuary roof. The church involved held what is known as an all-risk policy, a type of insurance contract that typically covers every direct physical loss unless it is specifically excluded within the document. However, the insurer denied the claim for the $1.1 million in damages, asserting that the weight of the ice and snow was not the primary cause of the collapse. Instead, the carrier pointed to several policy exclusions, including hidden or latent defects, general deterioration, and long-term corrosion. They argued that the roof had inherent flaws that would have eventually led to failure regardless of the weather conditions. This denial forced the policyholder into a protracted legal battle, illustrating the common tactics used by insurers to avoid large payouts by focusing on pre-existing structural conditions rather than the immediate incident.
Examining the Burden of Proof
During the four-day jury trial, the litigation essentially became a high-stakes battle between engineering experts. The policyholder’s engineering consultant testified that the sliding of ice and snow during the storm was the definitive causative agent that triggered the collapse, while the insurer’s expert countered that the damage was purely the result of excluded wear and tear over time. The jury’s decision to side with the church was a monumental victory for policyholders, signaling that juries are often skeptical of an insurer’s attempt to minimize the impact of a major weather event. By affirming the verdict, the Fourth Circuit validated the district court’s jury instructions and the overall approach to evidence in these cases. This validation means that insurers cannot simply point to minor maintenance issues to escape their financial responsibilities. The ruling confirms that the burden of proof for an exclusion is remarkably high, requiring the insurer to prove that the damage occurred solely due to an excluded peril.
Redefining Causation in Insurance Law
Clarifying the Causation Standard
Central to the court’s reasoning was the clarification of the causation standard applied to all-risk policies within the state. For years, insurance companies have advocated for the efficient proximate cause standard, which suggests that a covered peril must be the predominant or most significant factor in a loss to trigger coverage. If a court were to apply this standard strictly, an insurer might avoid payment if they could prove that a non-covered factor, such as a construction defect, was fifty-one percent responsible for the damage. However, North Carolina’s judicial system has increasingly leaned toward the concurrent causation or all-risk standard. This model recognizes that multiple factors often contribute to a single loss. Under this framework, if a covered event like a hurricane or a snowstorm plays any role in the damage, the policy is triggered. This standard reflects the intended purpose of all-risk insurance, which is to protect against the unexpected and the fortuitous.
Establishing the Sole Cause Requirement
The application of the sole cause requirement for exclusions represents a significant hurdle for insurers trying to limit their liability. In North Carolina, for an exclusion to successfully bar a claim, the insurance company must demonstrate that the excluded peril was the only reason the loss occurred. If a non-excluded cause, such as wind or snow, contributes even a small percentage to the total damage, the insurer remains on the hook for the entire claim. This all-or-nothing approach effectively prevents insurance companies from splitting hairs to find minor structural defects as a means to void a claim after a major catastrophe. It simplifies the recovery process for policyholders who would otherwise face the nearly impossible task of mathematically segregating damages between covered and non-covered causes. By maintaining this high bar, the courts ensure that the broad promises made in an all-risk policy are kept, providing a level of financial predictability that is essential for businesses and non-profits.
Broader Judicial Trends and Strategic Outcomes
Reviewing the Broader Judicial Trend
The precedent set in the church case is further strengthened when viewed alongside the North Carolina Supreme Court’s 2024 ruling regarding business interruption. In that landmark decision, the court held that the phrase direct physical loss could be interpreted to include the loss of use and access to a property due to government-mandated closure orders. While many other state courts across the United States took a much more conservative approach and rejected similar claims, North Carolina stood out by favoring the reasonable expectations of the policyholder. This consistent trend across different levels of the judiciary indicates a unified philosophy that prioritizes the plain meaning of policy language. It assumes that if an insurer drafts an ambiguous contract, that ambiguity must be strictly construed against the drafter. This environment has transformed the state into a significant outlier, offering a powerful blueprint for how modern insurance contracts should be interpreted in the current year.
Strategic Outcomes and Practical Resolutions
In light of these developments, policyholders were encouraged to adopt proactive strategies when filing claims. The legal community recommended that organizations engaged qualified engineering experts immediately after a loss to provide unhedged opinions connecting the damage to covered perils. Attorneys advised their clients to vigorously challenge any insurer that attempted to apply the restrictive efficient proximate cause standard instead of the state’s preferred concurrent causation model. Many businesses reviewed their existing policies to ensure their coverage limits aligned with the broad interpretations now supported by the Fourth Circuit. By documenting all contributing factors and leveraging the sole cause requirement, policyholders successfully navigated the claims process. These judicial rulings ultimately provided a clearer path for recovery, forcing insurers to adhere to the expansive promises of all-risk coverage. Consequently, the burden of managing property damage became more manageable as the legal system favored transparency over technical exclusions.