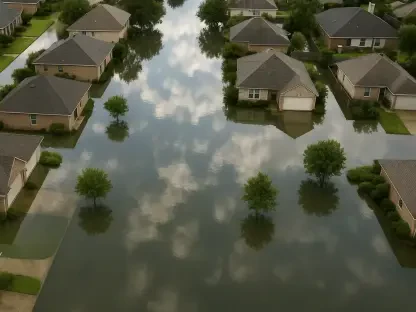
The $40 billion in insured losses from the 2025 Los Angeles wildfires has created an unprecedented volume of legal claims now circulating through opaque financial markets. This massive financial fallout has transformed the aftermath of natural disasters into a high-stakes arena for alternative asset managers and hedge funds. As the recovery efforts for the Eaton and Palisades fires continue throughout 2026, a sophisticated secondary market has emerged where legal subrogation rights are traded like distressed debt. Investors are purchasing these rights from insurance companies that are eager to offload the uncertainty of multi-year litigation in exchange for immediate liquidity. This shift represents a fundamental change in how disaster recovery is financed, moving it away from traditional actuarial models toward speculative investment strategies. While the human cost of the fires remains the primary focus, the financial sector sees a landscape of quantified risk and potential recovery that offers yields uncorrelated with broader market trends.
Legal Frameworks: The Foundation of Subrogation Trading
The Doctrine: Strict Liability and Inverse Condemnation
The legal foundation for this burgeoning market lies in the California doctrine of inverse condemnation, which effectively imposes strict liability on utilities for damages caused by their equipment. This specific legal framework means that entities like Southern California Edison can be held responsible for wildfire damages even if they were not found to be negligent in their operations. For investors, this doctrine provides a relatively clear path to recovery, as the focus remains on the physical origin of the fire rather than the intent or carelessness of the utility company. Because the Eaton fire has been linked to utility infrastructure, the certainty of eventual payouts has incentivized hedge funds to build massive portfolios of these claims. Financial analysts have observed that this legal environment creates a unique asset class where the primary variable is the time to settlement rather than the legal validity of the claim itself. This predictability has solidified California’s status as a primary hub for subrogation trading.
Market Mechanics: Pricing the Secondary Claims Market
Valuing these claims requires a complex analysis of potential settlement amounts versus the immediate cash needs of the original insurers. Hedge funds typically acquire subrogation rights at significant discounts, often paying between thirty and sixty cents on the dollar depending on the perceived strength of the evidence. This pricing reflects the inherent risks of protracted litigation and the possibility of future legislative interference that could cap utility liabilities. For insurance companies, selling these claims allows them to shore up their balance sheets and satisfy regulatory capital requirements after paying out billions to policyholders. Conversely, the purchasing funds are betting on their ability to negotiate higher settlements or win at trial, targeting internal rates of return in the low-to-mid teens. This dynamic has created a specialized ecosystem of legal experts and financial modelers who spend 2026 refining algorithms to predict the outcome of the thousands of lawsuits currently pending in the state court system.
Legislative Responses and Strategic Outlook
Legislative Response: The Impasse of State Oversight
In response to the growing influence of Wall Street in disaster recovery, California lawmakers attempted to curb the speculative trading of wildfire claims through several legislative proposals. Governor Gavin Newsom introduced a right of first refusal, which theoretically required insurance companies to offer subrogation claims to the utilities themselves before selling them to third-party investors. However, this policy proved largely ineffective because the utilities, already burdened by massive debts and the ongoing costs of infrastructure hardening, lacked the necessary capital to exercise these rights. The failure of the state legislature to pass a comprehensive ban on these transactions signaled to the financial markets that the subrogation trade would remain a legal and profitable enterprise. Critics argued that these financial maneuvers allowed outside entities to profit from the state’s misfortune, yet the practical reality of the insurance industry’s need for liquidity outweighed these moral concerns.
Strategic Outlook: Future Settlements and Risk Integration
The financial landscape for wildfire claims moved toward a critical juncture as the market prepared for the upcoming bellwether trials scheduled for early 2027. These legal proceedings were expected to set the pricing benchmarks for thousands of outstanding claims related to the Eaton fire, providing much-needed clarity for both plaintiffs and investors. Most market participants concluded that the integration of legal claims into mainstream financial portfolios was no longer a temporary trend but a permanent fixture of the catastrophe recovery process. Strategic advice for stakeholders centered on the development of more transparent reporting standards to mitigate the opacity that currently defines these private transactions. Furthermore, the stabilization of this market suggested that utilities would need to explore more robust insurance-linked securities to manage their future liabilities. As the 2026 cycle of litigation progressed, the secondary market for subrogation rights successfully transitioned into a structured component of institutional risk management.