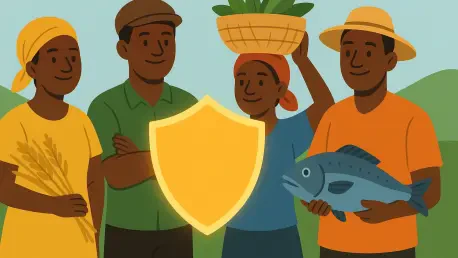
Government directives now require the Tanzania Insurance Regulatory Authority to intensify outreach specifically for rural farmers, fishers, and small-scale traders. This strategic mandate follows an extraordinary period of financial evolution in 2025, during which the national insurance sector experienced a monumental surge of 68.4% in Gross Written Premiums, totaling TZS 2.55 trillion. This growth is not a mere byproduct of general economic expansion but is the direct result of the Universal Health Insurance Act, which has effectively repositioned insurance from a specialized financial product for the wealthy into a mandatory pillar of national life. By integrating the National Health Insurance Fund contributions into broader market data and mandating coverage, the state has fundamentally altered the nation’s financial trajectory. This transformation signifies a departure from a fragmented informal economy toward a structured system where millions of citizens are now recognized participants in the formal financial ecosystem. The ripple effects of this integration are becoming increasingly evident as households that once lived on the edge of financial ruin due to medical emergencies now find themselves protected by a robust safety net. This newfound security is encouraging a broader culture of investment and savings, as the fear of catastrophic health expenditures recedes. Consequently, the insurance industry is no longer operating on the fringes of the Tanzanian economy; it has become a central engine for domestic capital mobilization and long-term economic resilience.
Measuring Macroeconomic Gains: The Surge in Market Penetration
The macroeconomic impact of this insurance revolution is perhaps most visible in the rising contribution of the sector to the national Gross Domestic Product. In 2025, insurance penetration reached a historic height of 2.11%, a significant increase from the 2.08% recorded in 2024 and a massive leap from the 1.68% seen in 2021. While these figures indicate substantial progress, they also point toward a horizon of untapped potential when compared to regional peers such as South Africa or Mauritius. The broader finance and insurance sector has emerged as the fastest-growing component of the Tanzanian economy, posting a staggering 15.7% growth rate. This acceleration demonstrates that the industry is successfully capturing value that was previously lost to informal risk-sharing mechanisms. By formalizing these financial flows, the government is creating a more transparent and taxable economic environment, which in turn provides the state with the necessary resources to reinvest in public infrastructure. The insurance sector now accounts for nearly 29% of the total contribution from the finance and insurance industry to the GDP, proving that the mandatory nature of health coverage has served as a master key for unlocking broader economic participation across all regions.
Beyond the high-level GDP figures, the shift in insurance density offers a more granular look at how individual Tanzanians are engaging with the financial system. In 2025, the average premium spent per person rose by 63.7% to TZS 37,455, a clear indicator that the “insurance culture” is taking root at the grassroots level. This spike in density is mirrored by the total number of policyholders and beneficiaries, which has climbed to 26.8 million people. Representing nearly 40% of the estimated population of 68.1 million, this demographic shift means that almost half of the country is now connected to a formal risk-mitigation framework. This is a profound change from just a few years ago when insurance was largely synonymous with motor vehicle coverage in urban centers. Today, the demographic profile of an insurance holder is far more diverse, including rural agricultural workers and small-scale entrepreneurs who were previously excluded from the formal banking and insurance sectors. This broadening of the risk pool not only stabilizes the insurance providers themselves by diversifying their portfolios but also provides a more stable foundation for the nation’s banking sector, as insured individuals are often viewed as more creditworthy and less prone to loan defaults caused by personal health crises.
The Health Sector Revolution: A Catalyst for Infrastructure Growth
The most dramatic transformation within the industry has occurred in the health insurance segment, which saw its Gross Written Premiums skyrocket by more than 400% in 2025. This fivefold increase, bringing the total to TZS 986.6 billion, was almost entirely driven by the legislative mandate of the Universal Health Insurance Act. Health insurance has now overtaken several traditional categories to command nearly 39% of the total insurance market, compared to just 12.4% in previous reporting cycles. This rapid expansion is led by the public sector, with the National Health Insurance Fund serving as the primary vehicle for this transition. However, the private sector is also showing significant movement, accounting for nearly 29% of the health segment’s total contributions. The infusion of such massive amounts of capital into the health sector is creating a virtuous cycle of investment and improvement. As the pool of insured citizens grows, the demand for high-quality medical services is increasing, which in turn provides the necessary funding for healthcare providers to upgrade their facilities, purchase modern diagnostic equipment, and hire specialized medical personnel. This capital influx is effectively privatizing the burden of healthcare costs while simultaneously socializing the benefits of high-quality medical care across a much larger segment of the population.
The sheer scale of this insurance mandate has also triggered an unprecedented expansion in the nation’s medical infrastructure and service provider network. Within a single year, the number of registered service providers endorsed under the Universal Health Insurance Act jumped from approximately 1,700 to over 10,000. This massive spike reflects the urgency with which medical facilities, both public and private, have sought to align themselves with the new regulatory environment to gain access to the growing pool of insured patients. This expansion is particularly crucial for rural areas, where medical facilities were historically underfunded and underutilized due to the inability of local residents to pay for services out-of-pocket. Now, with insurance coverage becoming the norm, these facilities have a guaranteed stream of income, allowing them to remain operational and improve their standards of care. The endorsement of such a vast number of facilities also facilitates better data collection and quality control by the Tanzania Insurance Regulatory Authority and the Ministry of Health. By monitoring the performance and claim patterns of these 10,000 providers, the state can identify gaps in service delivery and strategically direct future investments to ensure that the promise of universal coverage translates into actual health outcomes for every citizen.
Portfolio Diversification: Beyond Mandatory Health Coverage
While the headlines were dominated by the health insurance boom, the general insurance segment remained a critical component of the market, representing nearly 45% of total volume in 2025. Motor insurance continues to lead this category, but the most interesting development is the rapid growth of the travel insurance sector. Following the implementation of Finance Act No. 11 of 2025, which mandated inbound travel insurance for foreigners entering Mainland Tanzania, the segment more than tripled in value. This policy ensures that the burgeoning tourism industry provides a direct financial benefit to the local insurance market while protecting the national healthcare system from the costs of treating uninsured visitors. In Zanzibar, the impact was even more pronounced, with mandatory travel insurance accounting for nearly 70% of the island’s total Gross Written Premiums. This localized success story demonstrates how targeted regulatory interventions can leverage specific regional economic strengths to build a robust financial foundation. By linking insurance to high-traffic economic activities like tourism, the government has created a sustainable revenue stream that supports the broader insurance ecosystem without placing additional financial burdens on domestic taxpayers.
The evolution of the Tanzanian market is also characterized by a maturing demand for specialized insurance products that cater to the country’s diverse cultural and religious landscape. Life insurance, for instance, grew by 16.1%, largely driven by group credit life policies that are now standard requirements for obtaining bank loans. This synergy between the insurance and banking sectors is essential for the growth of the Tanzanian middle class, as it provides a safety net for families who take on debt to start businesses or purchase homes. Furthermore, the rise of Takaful, or Islamic insurance, which grew by nearly 40% in 2025, highlights the regulator’s success in creating an inclusive market. By providing products that comply with Islamic principles, the industry has opened its doors to a significant portion of the population that previously avoided traditional insurance for religious reasons. This diversification into niche markets like Takaful and weather-indexed agricultural insurance for maize and tobacco farmers is critical for long-term stability. It ensures that the insurance sector is not dependent on a single product or demographic but is instead a multifaceted industry capable of meeting the varied needs of a dynamic and growing nation.
Institutional Resilience: Strengthening the Financial Backbone
The credibility of any insurance market rests on its ability to pay claims promptly and fairly, and the Tanzanian sector has shown remarkable resilience in this regard. In 2025, the total claims paid by the industry surged by 136.4% to TZS 1.29 trillion, with the overall settlement ratio improving to over 80%. This high performance, particularly in the health and life segments, has been vital in building public trust during a period of rapid transition. The financial health of the companies themselves remains robust, with total assets rising by nearly 65% to TZS 4.06 trillion. This wealth is not merely sitting in bank accounts; a significant portion is invested in government securities and bank deposits, which in turn funds national development projects and provides liquidity to the banking system. The profitability of the sector has also reached new heights, with life insurers seeing a staggering 234% increase in profit after tax. These strong financial indicators suggest that the industry is well-capitalized and capable of handling the increased risks associated with a larger pool of policyholders. This stability is a prerequisite for the next phase of economic expansion, as it provides the confidence necessary for international investors to participate in the Tanzanian market.
The regulatory environment, under the guidance of the Tanzania Insurance Regulatory Authority, has kept pace with this growth through the implementation of modernization initiatives and digital reforms. The introduction of a regulatory sandbox is set to revolutionize the way insurance is sold and managed by providing a safe environment to test mobile-based microinsurance products. This digital transformation is particularly important for reaching the “last mile” of the population—those rural farmers and traders identified in the government’s latest directives. By leveraging Tanzania’s high mobile money penetration, insurers can now collect premiums and settle claims instantly, bypassing the need for physical branch networks in remote areas. Furthermore, the authority’s proactive stance in placing unstable firms under statutory management and issuing new guidelines for risk-based capital adequacy has sent a clear signal that the market is being governed with a focus on consumer protection and long-term sustainability. As the industry looks toward the coming years, the focus remains on refining these digital tools and finalizing legislative updates that will align the insurance sector with the modern economic realities of a digital-first world.
Strategic Pathways: The Future of Economic Integration
The regulatory framework established a clear path for the insurance sector to transition from a secondary financial service into a primary driver of national economic stability. The authority prioritized the expansion of mandatory coverage areas, ensuring that the pool of insured individuals remained large enough to maintain low premiums while providing comprehensive benefits. This approach successfully mitigated the risks of adverse selection and provided the insurance companies with the steady cash flow needed to invest in long-term infrastructure. The government’s decision to integrate health insurance into the national identity framework was a masterstroke of policy, as it effectively streamlined the enrollment process for millions of people who were previously outside the formal system. This integration simplified the administrative burden for both the state and the insurance providers, allowing for more efficient data management and faster claims processing.
The industry also moved toward higher transparency by adopting international reporting standards and enhancing the oversight of the reinsurance market. By requiring a significant portion of reinsurance to be handled locally, the state ensured that capital remained within the country to fund domestic projects rather than being exported to international markets. The Tanzania Insurance Regulatory Authority took decisive steps to address the increase in insurance fraud by implementing sophisticated digital tracking systems that cross-referenced claims across different providers. These technological advancements, combined with the successful rollout of the Universal Health Insurance scheme, transformed the financial landscape into a more predictable and secure environment. This strategic evolution provided the necessary confidence for local and foreign investors to commit significant capital to the Tanzanian market, ensuring that the insurance sector remained a cornerstone of the nation’s journey toward a more resilient and inclusive economy.