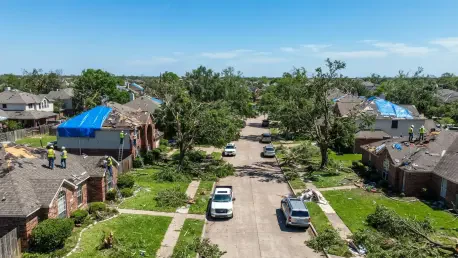
The global financial ecosystem currently relies on an insurance market that must simultaneously absorb the shocks of climate instability while capitalizing on the highest interest rates seen in a generation. In 2026, the industry has reached a critical crossroads where the stability of commercial enterprises and the safety of individual consumers depend on how well carriers manage their risk appetites in an unpredictable weather environment. This sector serves as a cornerstone of economic resilience, providing the necessary safety nets for the world’s most vulnerable supply chains. Currently, the market is characterized by a “hard” pricing environment in casualty lines, yet it simultaneously faces growing pressure in property segments due to a decade-high frequency of secondary perils such as convective storms and localized flooding.
Technological integration has moved from being a luxury to a primary differentiator for market leaders seeking to maintain profitability. Predictive modeling and AI-driven underwriting are now the essential tools used to separate sustainable growth from catastrophic exposure. Simultaneously, regulatory scrutiny regarding capital adequacy and environmental, social, and governance disclosures is intensifying, forcing major players to refine their balance sheets while maintaining robust solvency ratios. The current landscape demands a high degree of transparency and ethical governance, as investors look for firms that can marry traditional underwriting discipline with modern, tech-forward investment and risk-assessment models.
Strategic Performance and Market Dynamics in a Shifting Climate
Emerging Trends and the Evolution of Risk Management
The third quarter of 2026 has highlighted a definitive shift in corporate risk mitigation where insurers are increasingly prioritizing discipline over sheer volume. This trend is visible in how major carriers like AIG are intentionally retreating from underpriced property risks in North America to protect their long-term interests. By focusing on quality rather than quantity, these firms are insulating themselves from the volatility that has historically eroded margins during active storm seasons. Advanced tools such as satellite imagery and real-time data analytics are now being leveraged to price risks more accurately, allowing insurers to adjust premiums in real time as weather patterns evolve.
Furthermore, the rise of the high-net-worth personal lines segment has opened new avenues for profitable growth in an otherwise crowded market. Affluent clients are increasingly seeking comprehensive protection packages that bundle property, casualty, and health coverage into single, high-limit policies. This shift toward holistic coverage is driven by a growing awareness of global instability, prompting a demand for insurers that can offer tailored solutions for complex asset portfolios. As a result, carriers that have invested in specialized retail casualty units are finding more success in maintaining loyalty among high-value customers.
Quantifying Growth: Performance Indicators and 2027 Projections
AIG’s performance offers a revealing roadmap for industry expectations heading into the next fiscal period. While the company reported an adjusted earnings per share of $2.06, which represented a slight decline compared to the previous year, this figure still significantly outperformed the Wall Street consensus of $1.89. This “beat” indicates that the market had likely overestimated the negative impact of recent catastrophe losses on the company’s bottom line. The year-to-date trajectory remains robust, with adjusted earnings per share rising over 20% to $6.18, signaling that the core business remains fundamentally sound despite external pressures.
Projections for 2027 indicate a pivot toward international expansion as a primary driver of future revenue. AIG’s international commercial premiums have already shown a 13% growth rate, reaching $2.4 billion this quarter. If the current 140-basis-point improvement in the combined ratio persists, the industry can expect continued profitability across global segments. Analysts are watching the international markets closely, as these regions often offer more favorable pricing dynamics compared to the heavily litigious and weather-exposed North American property market.
Overcoming the Turbulence of Catastrophic Weather and Pricing Pressures
The primary obstacle facing the insurance industry today is the rising cost associated with “secondary perils,” which include severe convective storms, hail, and high winds. These events have surpassed $50 billion in annual insured losses for three consecutive years, fundamentally changing the risk profile for property underwriters. AIG felt this pressure acutely in the third quarter of 2026, as catastrophe charges surged to $283 million. This was a stark contrast to the $100 million reported in the previous year, highlighting how quickly a single season of localized weather events can impact an underwriting portfolio.
To combat these rising costs, insurers are adopting more aggressive capital return strategies and maintaining strict debt-to-total-capital ratios to ensure liquidity. This financial prudence is coupled with a struggle against social inflation in North American casualty lines, where legal costs and jury awards are driving up the cost of claims. Companies are now utilizing sophisticated reserve management and a specialized retail focus to offset thinning margins. Maintaining a healthy balance between property and casualty books has become a vital survival strategy in an environment where traditional property business is under constant threat from climate-driven losses.
The Regulatory Environment and Compliance Standards for 2026
The regulatory landscape is becoming increasingly complex as authorities demand greater transparency regarding climate-related financial risks. Significant legislative updates throughout 2026 have focused on ensuring that insurers maintain adequate reserve releases to cover potential future liabilities. AIG’s recent reduction in favorable reserve releases, which dropped to 1.4 points from 5.9 points previously, reflects a more cautious approach to reporting. This shift is a direct response to a compliance-heavy environment where regulators are looking to prevent insurers from inflating current profits at the expense of future solvency.
Security measures regarding data privacy in the digital underwriting process are also under the microscope of federal and international agencies. New standards require rigorous audits of algorithmic bias, ensuring that the AI models used for pricing do not unfairly discriminate against certain demographics or geographic regions. Compliance is no longer just a legal necessity but a strategic pillar used to reassure investors of a company’s long-term sustainability. Companies that can demonstrate ethical governance and robust data protection are finding it easier to attract capital and maintain a favorable reputation in a skeptical market.
Innovation and the Future Trajectory of Global Underwriting
Looking forward, the insurance industry is poised for a period of radical innovation driven by leadership transitions and digital transformation. As Eric Andersen takes the helm at AIG, the focus is shifting toward meeting long-term financial targets through a diversified global footprint. This approach balances the volatility inherent in North American markets with the strength of international operations. Leadership is increasingly looking at how technology can streamline the claims process and improve the customer experience, turning insurance from a grudge purchase into a proactive risk management partnership.
Disruptors such as Hurricane Isaias and other climate events will continue to test the industry’s resilience, but the integration of fixed-income investment strategies provides a necessary buffer. AIG’s general insurance investment income grew by 9% this quarter, demonstrating the value of a high-yielding fixed-income portfolio in a high-interest-rate environment. The future of the sector lies in the ability to marry traditional underwriting discipline with agile, tech-forward investment and risk-assessment models. This hybrid approach allows firms to generate steady returns even when catastrophe losses challenge their primary underwriting operations.
Summarizing the Financial Outlook and Investment Prospects
The financial results for the third quarter of 2026 demonstrated that a resilient enterprise could outperform expectations even when faced with significant underwriting pressure. AIG’s 44% jump in personal lines underwriting income provided a necessary counterweight to the challenges faced in the commercial property sector, highlighting the benefits of a diversified business model. The company successfully executed an aggressive share buyback program, returning $527 million to shareholders while increasing the adjusted book value per share to $81.25. These results suggested that the underlying fundamentals of the company remained strong, providing a solid foundation for the fiscal year ahead.
Leadership began prioritizing the development of parametric insurance solutions to address the protection gaps caused by increasing climate volatility in the 2026 to 2028 period. Investors focused on the long-term value creation potential of firms that could successfully navigate the rising costs of secondary perils without sacrificing pricing discipline. Strategic shifts toward international markets and high-net-worth segments indicated a move toward higher-margin, lower-volatility business. These actions ensured that the industry remained a vital part of the global economy, providing the stability and capital necessary to support growth in an increasingly uncertain world.