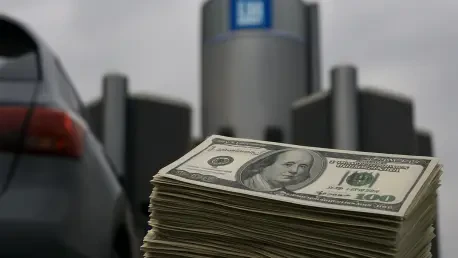
Drivers are often unaware that companies like LexisNexis maintain detailed C.L.U.E. reports containing up to seven years of personal property and auto claims history. This specialized data ecosystem operates largely in the background, yet it holds immense power over the financial lives of millions of motorists across the United States. Recently, General Motors reached a landmark $220 million settlement following allegations from 35 states and the District of Columbia that the automaker harvested and sold sensitive driving behavior data without adequate disclosure. Between 2016 and 2024, millions of individuals enrolled in the Smart Driver program, often under the impression that they were simply receiving helpful safety feedback or improving their driving habits. Instead, this granular information detailing everything from hard braking events to high-speed acceleration was funneled to third-party data brokers who then sold the insights to insurance providers.
1. The Impact of Telematics on Modern Insurance Pricing
The technical infrastructure of modern vehicles allows for the constant transmission of telematics, a feature that General Motors utilized extensively through its OnStar services. While the stated goal was often presented as a way to enhance road safety and vehicle longevity, the legal challenge brought by state attorneys general highlighted a darker commercial reality. By tracking precise geolocation and specific driving patterns, the company compiled exhaustive profiles on individual behavior behind the wheel. The settlement finalized in late October addressed the specific claims that these profiles were weaponized against consumers in the insurance market. The $220 million payout serves as a significant deterrent, yet it also underscores the maturity of a data economy where personal habits are treated as high-value commodities. For the affected drivers, the breach of trust was compounded by the fact that data collection occurred over a decade.
Beyond the immediate financial penalty, the investigation revealed the intricate pathways through which consumer data travels once it leaves the vehicle’s onboard computer. Data brokers like LexisNexis Risk Solutions play a pivotal role in this exchange, acting as a clearinghouse for information that insurers use to determine the likelihood of future claims. When driving behavior data is integrated into these reports, it transforms a standard history of accidents and claims into a predictive model of potential liability. This transition has led to significant controversy, as motorists found themselves penalized for behaviors that had never actually resulted in an accident or a legal infraction. The reality of modern automotive technology is that every turn, stop, and start can be monetized, creating a persistent digital shadow that follows a person from one carrier to another. This systemic data sharing created an environment where drivers were essentially paying twice.
2. Regulatory Responses and Consumer Recovery Strategies
In response to these privacy concerns, the Federal Trade Commission issued a final order against General Motors and OnStar in January 2026, establishing a new framework for consumer data protection. This order prohibits the company from sharing geolocation and driving behavior data with consumer reporting agencies for a period of five years. Furthermore, for the next twenty years, General Motors must obtain affirmative express consent from every user before collecting or sharing any connected vehicle data. This shift toward opt-in models represents a fundamental change in how the automotive industry must handle personal information. It forces a level of transparency that was previously absent, requiring clear explanations of what data is being gathered and exactly who will have access to it. For consumers, this means the days of buried fine print are over, as the government has mandated that deletion requests and data access must be simplified for all U.S. customers.
Drivers who took proactive measures to secure their digital footprints found that the most effective strategy involved a combination of administrative auditing and market competition. They requested their C.L.U.E. reports annually to ensure no phantom claims or incorrect telematics data distorted their risk profiles. When premiums shifted without a clear explanation, diligent consumers contacted their insurers to demand transparency regarding the use of third-party consumer reports. They also reviewed the privacy settings within their vehicle’s companion applications, disabling unnecessary data-sharing features that were not essential for safety or navigation. Furthermore, motorists compared quotes across multiple carriers every six months, recognizing that some insurers weighed telematics data differently than others. By maintaining an organized file containing their insurance renewals and corrected reports, they built a robust paper trail that served as a defense.