As capital becomes increasingly expensive, the traditional tension between tech-first startups and insurance-first incumbents is dissolving into a more integrated approach. This shift marks the transition from an era defined by aggressive market disruption and rapid customer acquisition to one
The insurance industry has historically operated under the heavy burden of monolithic technological infrastructures that stifle rapid innovation and prevent the seamless delivery of modern, customer-centric products. This legacy environment creates a persistent friction where carriers find
Digital transactions in the insurance sector have surged beyond expectations, forcing traditional oversight mechanisms to the brink of failure as sophisticated bad actors exploit systemic gaps. The core objective of modernizing fraud systems is to protect honest customers while building a more
A critical distinction is emerging between first-party loss coverage, third-party indemnity, and performance guarantees that compensate for model failures or hallucinations. As artificial intelligence moves from simple generative text to autonomous, multi-agent systems capable of managing sensitive
Applicants who cannot be automatically verified have a narrow ninety-five-day window to provide manual documentation before losing their temporary subsidies. This urgent requirement serves as a cornerstone of the 2025 Reconciliation Law, which has fundamentally restructured the relationship between
Legal proceedings in Miami-Dade reveal how a resident previously barred for organized crime managed to infiltrate and exploit a licensed insurance agency. The Florida Department of Financial Services recently uncovered a sophisticated scheme that operated under the guise of legitimacy for several
Applying scalable, AI-driven intelligence to every underwriting decision is becoming a necessity as environmental risks become increasingly more volatile. This fundamental shift in the global risk landscape has prompted Guidewire Software to initiate a transformative $2.1 billion acquisition of the
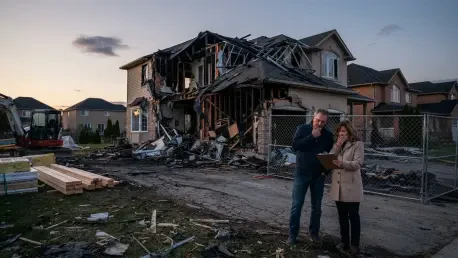
Underinsurance remains an invisible risk during the life of a policy and only reveals itself when the sum insured fails to cover a modern rebuild. The Australian housing market is currently grappling with a deceptive economic paradox that places thousands of homeowners at significant financial
Navigating the increasingly volatile global insurance market requires more than just high-level statistical models; it demands a seamless transition from back-office data science to front-line policy issuance without the typical months-long delays that plague legacy systems. The Q4 2026 release
Global insurance organizations managing over twenty-four trillion dollars in assets are transitioning from reactive crisis management toward a more selective approach to risk. This shift represents a fundamental maturation in how institutional investors approach global capital flows in 2026. While
1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24 25 26 27 28 29 30 31 32 33 34 35 36 37 38 39 40 41 42 43 44 45 46 47 48 49 50 51 52 53 54 55 56 57 58 59 60 61 62 63 64 65 66 67 68 69 70 71 72 73 74 75 76 77 78 79 80 81 82 83 84 85 86 87 88 89 90 91 92 93 94 95 96 97 98 99 100 101 102 103 104 105 106 107 108 109 110 111 112 113 114 115 116


