The insurance sector stands at a crossroads where the promise of hyper-automation meets the stubborn reality of decades-old operational habits. A critical bottleneck in current insurance operations involves the persistent need for manual intervention even when sophisticated artificial intelligence
As capital becomes increasingly expensive, the traditional tension between tech-first startups and insurance-first incumbents is dissolving into a more integrated approach. This shift marks the transition from an era defined by aggressive market disruption and rapid customer acquisition to one
The insurance industry has historically operated under the heavy burden of monolithic technological infrastructures that stifle rapid innovation and prevent the seamless delivery of modern, customer-centric products. This legacy environment creates a persistent friction where carriers find
Digital transactions in the insurance sector have surged beyond expectations, forcing traditional oversight mechanisms to the brink of failure as sophisticated bad actors exploit systemic gaps. The core objective of modernizing fraud systems is to protect honest customers while building a more
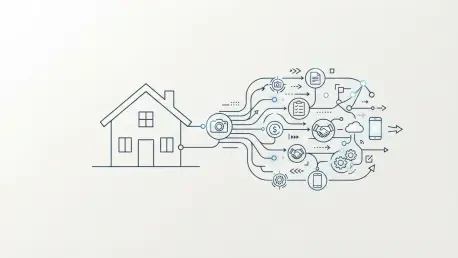
The ability to handle 90% of FNOL calls through Clara has proven that AI is no longer a pilot program but a foundational component of Hippo’s scaling strategy. This shift represents a fundamental change in how insurance providers manage the delicate balance between rapid customer acquisition and
Stable vendors backed by major private equity firms provide the financial security that mid-sized buyers weigh heavily when choosing long-term partners for core operational software. In the current 2026 insurance landscape, claims management has successfully transitioned from being a secondary
1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24 25 26 27 28 29 30 31 32 33 34 35 36 37 38 39 40 41 42 43 44 45 46 47 48 49 50 51 52 53 54 55 56