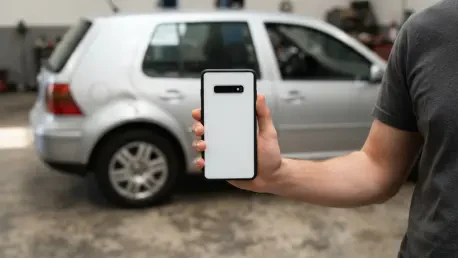
Digit Insurance utilized a guided app interface to decentralize the assessment process, allowing customers to capture visual evidence of vehicle damage without waiting for a third-party surveyor. Since its inception in 2017, the Bengaluru-based fintech company has worked to transform the insurance claims experience—traditionally a point of significant friction—into a defining brand asset. In a market where auto insurance serves as the primary touchpoint for millions of policyholders, Digit’s reliance on smartphone-enabled self-inspection and artificial intelligence represents a departure from traditional logistical bottlenecks. This shift is not merely about technical integration but reflects a deeper understanding of consumer behavior in an increasingly digital economy. By allowing users to handle assessments themselves, the firm bypassed the need for physical surveys that historically stalled repairs and settlement payouts.
The adoption of these technologies was a response to clear pain points within the Indian auto insurance sector. Previously, customers faced long delays while waiting for adjusters to visit accident sites or repair shops, a process that could take several days. Digit’s strategy capitalized on high smartphone penetration and the growing comfort consumers have with capturing high-quality visual data. This transition from a manual, expert-led survey to a user-driven digital experience has allowed the company to promise claim registration in a fraction of the time. This operational speed has become a core component of its market narrative, positioning the company as a disruptor capable of matching the expectations of a modern, fast-paced consumer base.
Navigating the Indian Insurance Landscape
Regulatory Framework: Navigating Local Rules
The operational landscape for any insurer in India is defined by the Insurance Regulatory and Development Authority of India. A key regulatory milestone occurred in 2024 with the issuance of a master circular regarding policyholder protection, which mandated that auto losses exceeding fifty thousand rupees must be inspected by a registered surveyor within twenty-four hours. However, this regulation also left significant room for digital innovation in the high-volume category of smaller claims. Digit successfully navigated these requirements by implementing its AI-driven self-inspection model specifically for these more frequent, lower-value losses, where the regulatory burden is less stringent.
By mid-2026, Digit established an overall market share of 3.1 percent, with a notably stronger footprint of 5.6 percent in the auto segment. This performance illustrates how the company carved out a niche by balancing the mandatory physical requirements for large-scale losses with an automated system for minor accidents. The hybrid ecosystem developed by the company ensures compliance with government standards while maximizing the efficiency of digital tools. This approach allowed the company to maintain growth without running afoul of the strict oversight that characterizes the Indian financial sector, creating a stable foundation for its rapid technological deployment.
Survey Delays: Removing the Human Bottleneck
The traditional model of auto insurance in the region often resulted in vehicles remaining stagnant in repair shops for days as policyholders waited for a third-party surveyor to arrive. This delay was a primary source of customer dissatisfaction and operational inefficiency. Digit’s core strategic objective focused on the radical acceleration of this timeline by eliminating the “wait” entirely. By providing a guided interface within its mobile application, the company empowered the average vehicle owner to act as an initial data collector, replacing the logistical nightmare of scheduling a physical visit with a process as simple as taking a photograph for social media.
This shift in responsibility from a professional surveyor to the consumer reduced the car claim inspection timeline from an average of seven days to approximately seven minutes. Such a massive reduction in turnaround time did more than just satisfy customers; it also lowered the overhead costs associated with dispatching human experts for every minor dent or scratch. By focusing on this specific behavioral insight—that modern consumers prefer immediate digital solutions over delayed manual ones—the company successfully rebranded the insurance claim from a bureaucratic chore into a streamlined digital interaction. This strategy effectively used operational performance as a primary driver for customer acquisition and brand loyalty.
Mechanics of Digital Execution
Inspection Flow: Documentation and AI Analysis
The technical execution of a claim within the Digit ecosystem follows a structured, paperless workflow designed for maximum accessibility. Before a user begins the visual assessment, they are prompted to have their Registration Certificate and driver’s license ready, as these are prerequisites for the validity of the digital claim. The application then guides the user through the process of capturing high-resolution photos or videos of the vehicle damage. This documentation is the cornerstone of the paperless model, ensuring that all necessary evidence is recorded at the point of impact or at the repair facility without requiring physical forms or signatures.
Once the visual evidence is uploaded, the company utilizes an advanced AI engine to evaluate the damage and automate the processing of related documents. In instances where the automated assessment requires additional scrutiny, the company employs remote video verification. This allows a claims handler to speak with the customer in real time or view the damage through a live stream, providing a layer of human oversight without the need for travel. This multi-tiered approach ensures that most claims are processed through the automated engine, while more complex cases receive targeted attention via high-definition video tools.
Performance Metrics: Tracking Approval Speed
To maintain its market position, the company has consistently highlighted its processing speed as a quantifiable promise to its policyholders. In its initial years of operation, the firm reported that eighty percent of auto claims were approved within twenty-four hours, while mobile phone insurance approvals reached ninety-three percent within the same window. These statistics served as proof of concept for the digital-first model, demonstrating that technology could indeed outpace traditional methods. By the second half of fiscal year 2025, the average auto repair approval time stood at roughly fourteen hours and forty-six minutes, maintaining a high standard of efficiency.
Further data from recent fiscal periods indicates that seventy-three percent of repair approvals for motorcycles and scooters were completed in under twelve hours. The auto claim settlement ratio reached ninety-six percent, a figure that reflects the company’s ability to process a vast majority of reported losses successfully. However, it is important to note that these settlement figures include both paid and closed claims, which encompasses rejected or withdrawn entries. Despite these nuances, the consistently high speed of repair approvals has remained the company’s most potent marketing tool, as it directly addresses the consumer’s need for a quick return to mobility after an accident.
Financial Trajectory and Transparency
Profitability Pivot: From Losses to Gains
Like many fintech startups, the company initially followed a trajectory characterized by significant early investment and subsequent losses as it sought to capture market share. In fiscal years 2021 and 2022, the firm recorded substantial negative earnings before achieving a turning point in 2023 with a profit of thirty-five point five crore rupees. This shift marked the beginning of a move toward sustainable growth, culminating in a profit after tax of four hundred twenty-five crore rupees by fiscal year 2025. This financial evolution demonstrated that the digital claims model was not just a high-cost customer acquisition strategy but a viable long-term business plan.
The successful public offering in May 2024, which saw the company’s shares subscribed nine point six times, further signaled investor confidence in the tech-forward financial model. While the company manages a high volume of premiums—exceeding ten thousand crore rupees in 2025—it continues to manage a combined ratio of 109.3 percent. This metric indicates that underwriting costs and claims payouts still exceed the premiums earned, with overall profitability being supported by investment income. As the company moves from 2026 to 2028, the primary financial challenge will be to reduce this ratio and achieve pure underwriting profitability through further automation and risk assessment refinements.
Radical Transparency: Public Accountability and Reports
A unique pillar of the company’s broader strategy has been the publication of detailed transparency reports. These documents provide the public with access to stage-wise turnaround times for various internal departments, creating a level of accountability rarely seen in the insurance industry. By allowing current and potential customers to see exactly how long each step of the claim process takes, the firm has converted its internal operational data into a powerful trust-building narrative. This strategy has helped the company distance itself from the general industry reputation for opacity and administrative delays.
This commitment to transparency extends across all product lines, including health insurance, where the company publishes approval times for both direct-billing and reimbursement flows. This consistent messaging ensures that the brand is associated with speed and clarity, regardless of the specific insurance product being used. By quantifying its promises and allowing for public verification, the firm has set a new standard for how financial services companies communicate with their clients. This approach not only builds credibility with the consumer but also forces internal teams to maintain high performance to meet the published benchmarks.
Strategic Implications: The Digital Claims Future
Regulatory Limits: Managing High-Value Losses
While the digital-only assessment model has revolutionized the processing of frequent, low-value claims, it faces a clear regulatory ceiling. Under current Indian law, claims exceeding the fifty thousand rupee threshold still require the involvement of registered third-party surveyors to ensure impartial assessment for larger financial liabilities. This means that for major accidents involving significant property damage or total loss, the self-inspection model serves as an acceleration layer rather than a complete replacement. The company must therefore maintain a hybrid infrastructure that integrates traditional survey methods with its digital front-end for these high-stakes cases.
Furthermore, a significant portion of the auto premium book is derived from third-party liability insurance. Unlike “own-damage” claims, which can be settled via an app interface, third-party claims are often subject to legal proceedings in Motor Accident Claims Tribunals. This creates a functional gap between the company’s digital marketing image and the legal reality of a substantial part of its financial portfolio. To address this, the firm has looked to extend its digital efficiency into the legal and documentation stages of third-party claims, aiming to reduce the time spent on litigation through better data collection and earlier settlement offers.
Operational Insights: Recommendations for Future Scalability
Analysis of the company’s trajectory reveals that the most effective strategy for sustaining growth involves a deliberate pivot toward profitability discipline over aggressive market expansion. Industry observers concluded that as the auto insurance market softened, the company’s decision to accept a slight contraction in market share while focusing on higher-margin policies was a necessary step for long-term health. It was established that the sustainability of the digital model depended on whether technological efficiency could finally drive the combined ratio below one hundred percent, transforming the claims process from a marketing asset into a superior financial engine.
Recommendations for the broader industry suggest that future success will likely involve the integration of AI-driven claims data with smart-city infrastructure and vehicle telematics. This could allow for even more proactive claim handling, where the insurer is notified of an accident the moment it occurs through onboard sensors. The transition toward this level of automation is the next logical step for firms that have already mastered smartphone-based inspection. By 2026, the company established a precedent where transparency and speed were no longer optional features but were the primary drivers of consumer trust and operational success in the competitive fintech landscape.